Newsflash | September 2026 | Thailand updates rules on tax penalty waivers and reductions
Introduction
On 2 July 2026, the Thai Revenue Department (TRD) introduced the Departmental Orders No. Tor. Por. 369/2569 and No. Tor. Por. 370/2569, amending the existing framework of tax penalty and surcharge relief. This includes revised refund deadlines, expanded relief for certain VAT-related errors, and increased approval powers for TRD officials.
Key changes
- Tax refund claims and certain surcharges are now subject to statutory deadlines and higher approval thresholds for TRD officials;
- Greater relief for early correction of late VAT registration, and expanded relief for certain VAT filing errors;
- More limited relief for mid-year CIT surcharges.
Statutory refund deadlines and higher TRD approval limits
Taxpayers seeking refunds of penalties or certain surcharges already paid must submit their claims within the applicable statutory tax refund period. The Order covers penalties related to income tax, value-added tax (VAT) and specific business tax, as well as surcharges on mid-year corporate income tax instalments.
At the same time, the approval limits within which designated TRD offices may approve penalty and surcharge relief have been increased. The new thresholds vary by office type: central tax audit and large business tax administration offices can now approve relief up to THB 2 million each, up from THB 500,000. Area revenue offices saw their limit rise from THB 100,000 to THB 500,000, while regional revenue offices received a significant increase from THB 300,000 to THB 1 million.
These expanded ceilings allow larger penalty cases to be resolved at the appropriate administrative level, streamlining the relief process and offering greater flexibility to businesses with significant VAT exposures.
No full waiver for mid-year CIT surcharges
The revised framework permits reductions of surcharges relating to mid-year corporate income tax instalments. However, it no longer provides for a full waiver.
Enhanced VAT relief for late registration and filing errors
Businesses that fail to register for VAT may qualify for a full penalty waiver where the due VAT is filed and paid with the first VAT return, within 30 days of exceeding the registration threshold.
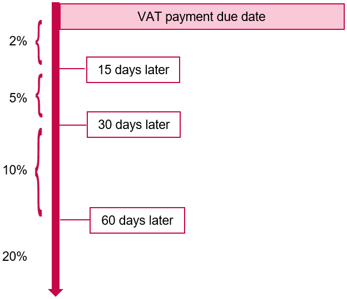
In cases where the correction occurs after the first VAT return, reduced penalty rates ranging from 2% to 20% may still be available. The applicable reduced penalty rate is therefore depends on the timing of the voluntary correction.
However, where the non-compliance was identified and documented by a tax officer before a voluntary correction, the reduced penalty rate will increase to 40% regardless of the timeline.
The Order also extends relief to certain VAT-related errors, including:
Incorrect assumptions that an activity was exempt from VAT registration;
Failure to recognize that the registration threshold had been exceeded; and
Duplicate VAT returns caused by online filing errors.
Please note that the provision of relief remains subject to the stipulated criteria and is not a guaranteed entitlement.